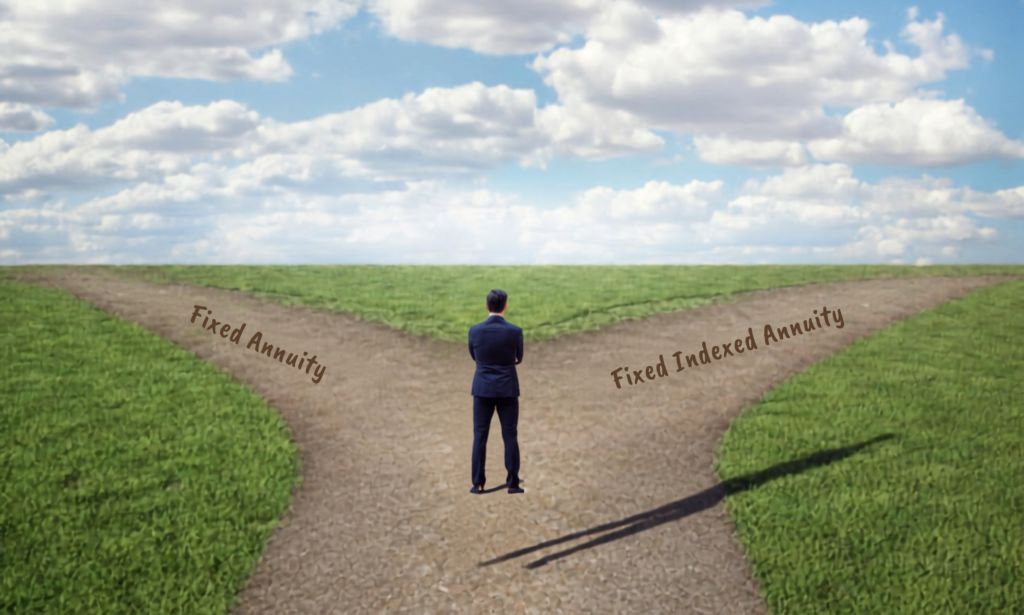
The right product begins with the client’s goal. When you’re comparing a fixed annuity versus a fixed indexed annuity, it’s easy to start with the products themselves. But for independent agents, the more useful starting point is when your client is sitting across from you. What do they want to accomplish? What matters most to them? Clarifying those priorities can make annuity product comparison much more focused. Instead of searching for a product and then determining where it fits, you can evaluate available options based on your client’s specific needs.
Start With Your Client’s Priorities
It’s important to start by clarifying what your client expects from this portion of their retirement strategy. Income may be a priority for one client, while another may be more concerned with protecting what they’ve already accumulated. Liquidity can also play an important role, particularly if your client thinks they may need access to a portion of the funds.
These priorities won’t necessarily point to a specific type of annuity. But they do give you a framework for comparing which options would be the best fit for your clients. It’s also important to consider when your client expects to need their money. Knowing their timeline and how an annuity fits with their other assets can help narrow the options before you need to start comparing specific ones.
Clarifying the Difference Between a Fixed Annuity and a Fixed Indexed Annuity
When comparing a fixed annuity to a fixed indexed annuity for a particular case, how the annuity earns interest is an important distinction. Fixed annuities offer a guaranteed interest rate for a set period, while fixed indexed annuities can potentially earn interest based on the performance of a market index. The more important question for you is how those differences align with each of your clients’ priorities. That becomes less about identifying the “best” product and more about identifying the features that matter most for the client in front of you.
Take a Closer Look at the Details
A thorough annuity product comparison goes beyond deciding between fixed and fixed indexed. Details about participation rates, caps, and spreads can all vary by product and should be evaluated based on current, approved carrier information. Additional features like surrender periods and charges, withdrawal provisions, income options, available riders, and other terms can all affect how well a particular annuity will align with your client’s priorities. This is where a more deliberate comparison becomes valuable. A feature that initially makes one product attractive may matter less once you consider the client’s full financial picture.
Consider the Carrier Along with the Contract
Product features are only part of the evaluation. An annuity is an insurance contract, so the financial strength and claims-paying ability of the issuing insurance company are important to consider as well. As an independent agent, you may have access to multiple carriers and a wide range of products. As you narrow the options for your client, consider the carrier alongside the guarantees, contract terms, and features you’re comparing. Each piece should support a recommendation that makes sense for your client’s goals.
Use Case Support to Make a Careful Comparison
Having experienced case support can also make the comparison process easier to navigate. Phase One Financial Group works with independent agents on both fixed and indexed annuities to provide hands-on support as you evaluate options for your clients. When an annuity may be appropriate for your client, Phase One can help you compare available options and consider how different product features align with the client’s goals. You have a knowledgeable resource in Phase One who understands your business and can stay involved as the case develops.
Keep the Goal at the Center of the Comparison
Comparing a fixed annuity to a fixed indexed annuity ultimately is about understanding what each option offers and determining how those features align with your client’s needs. A well-matched recommendation starts with clear client goals and careful comparison. When you have a case that deserves a closer look, wish to discuss an annuity case, or need support, Phase One is here to help. Connect with us on our website, email Brian at [email protected], or call today at (800) 849-5520.